

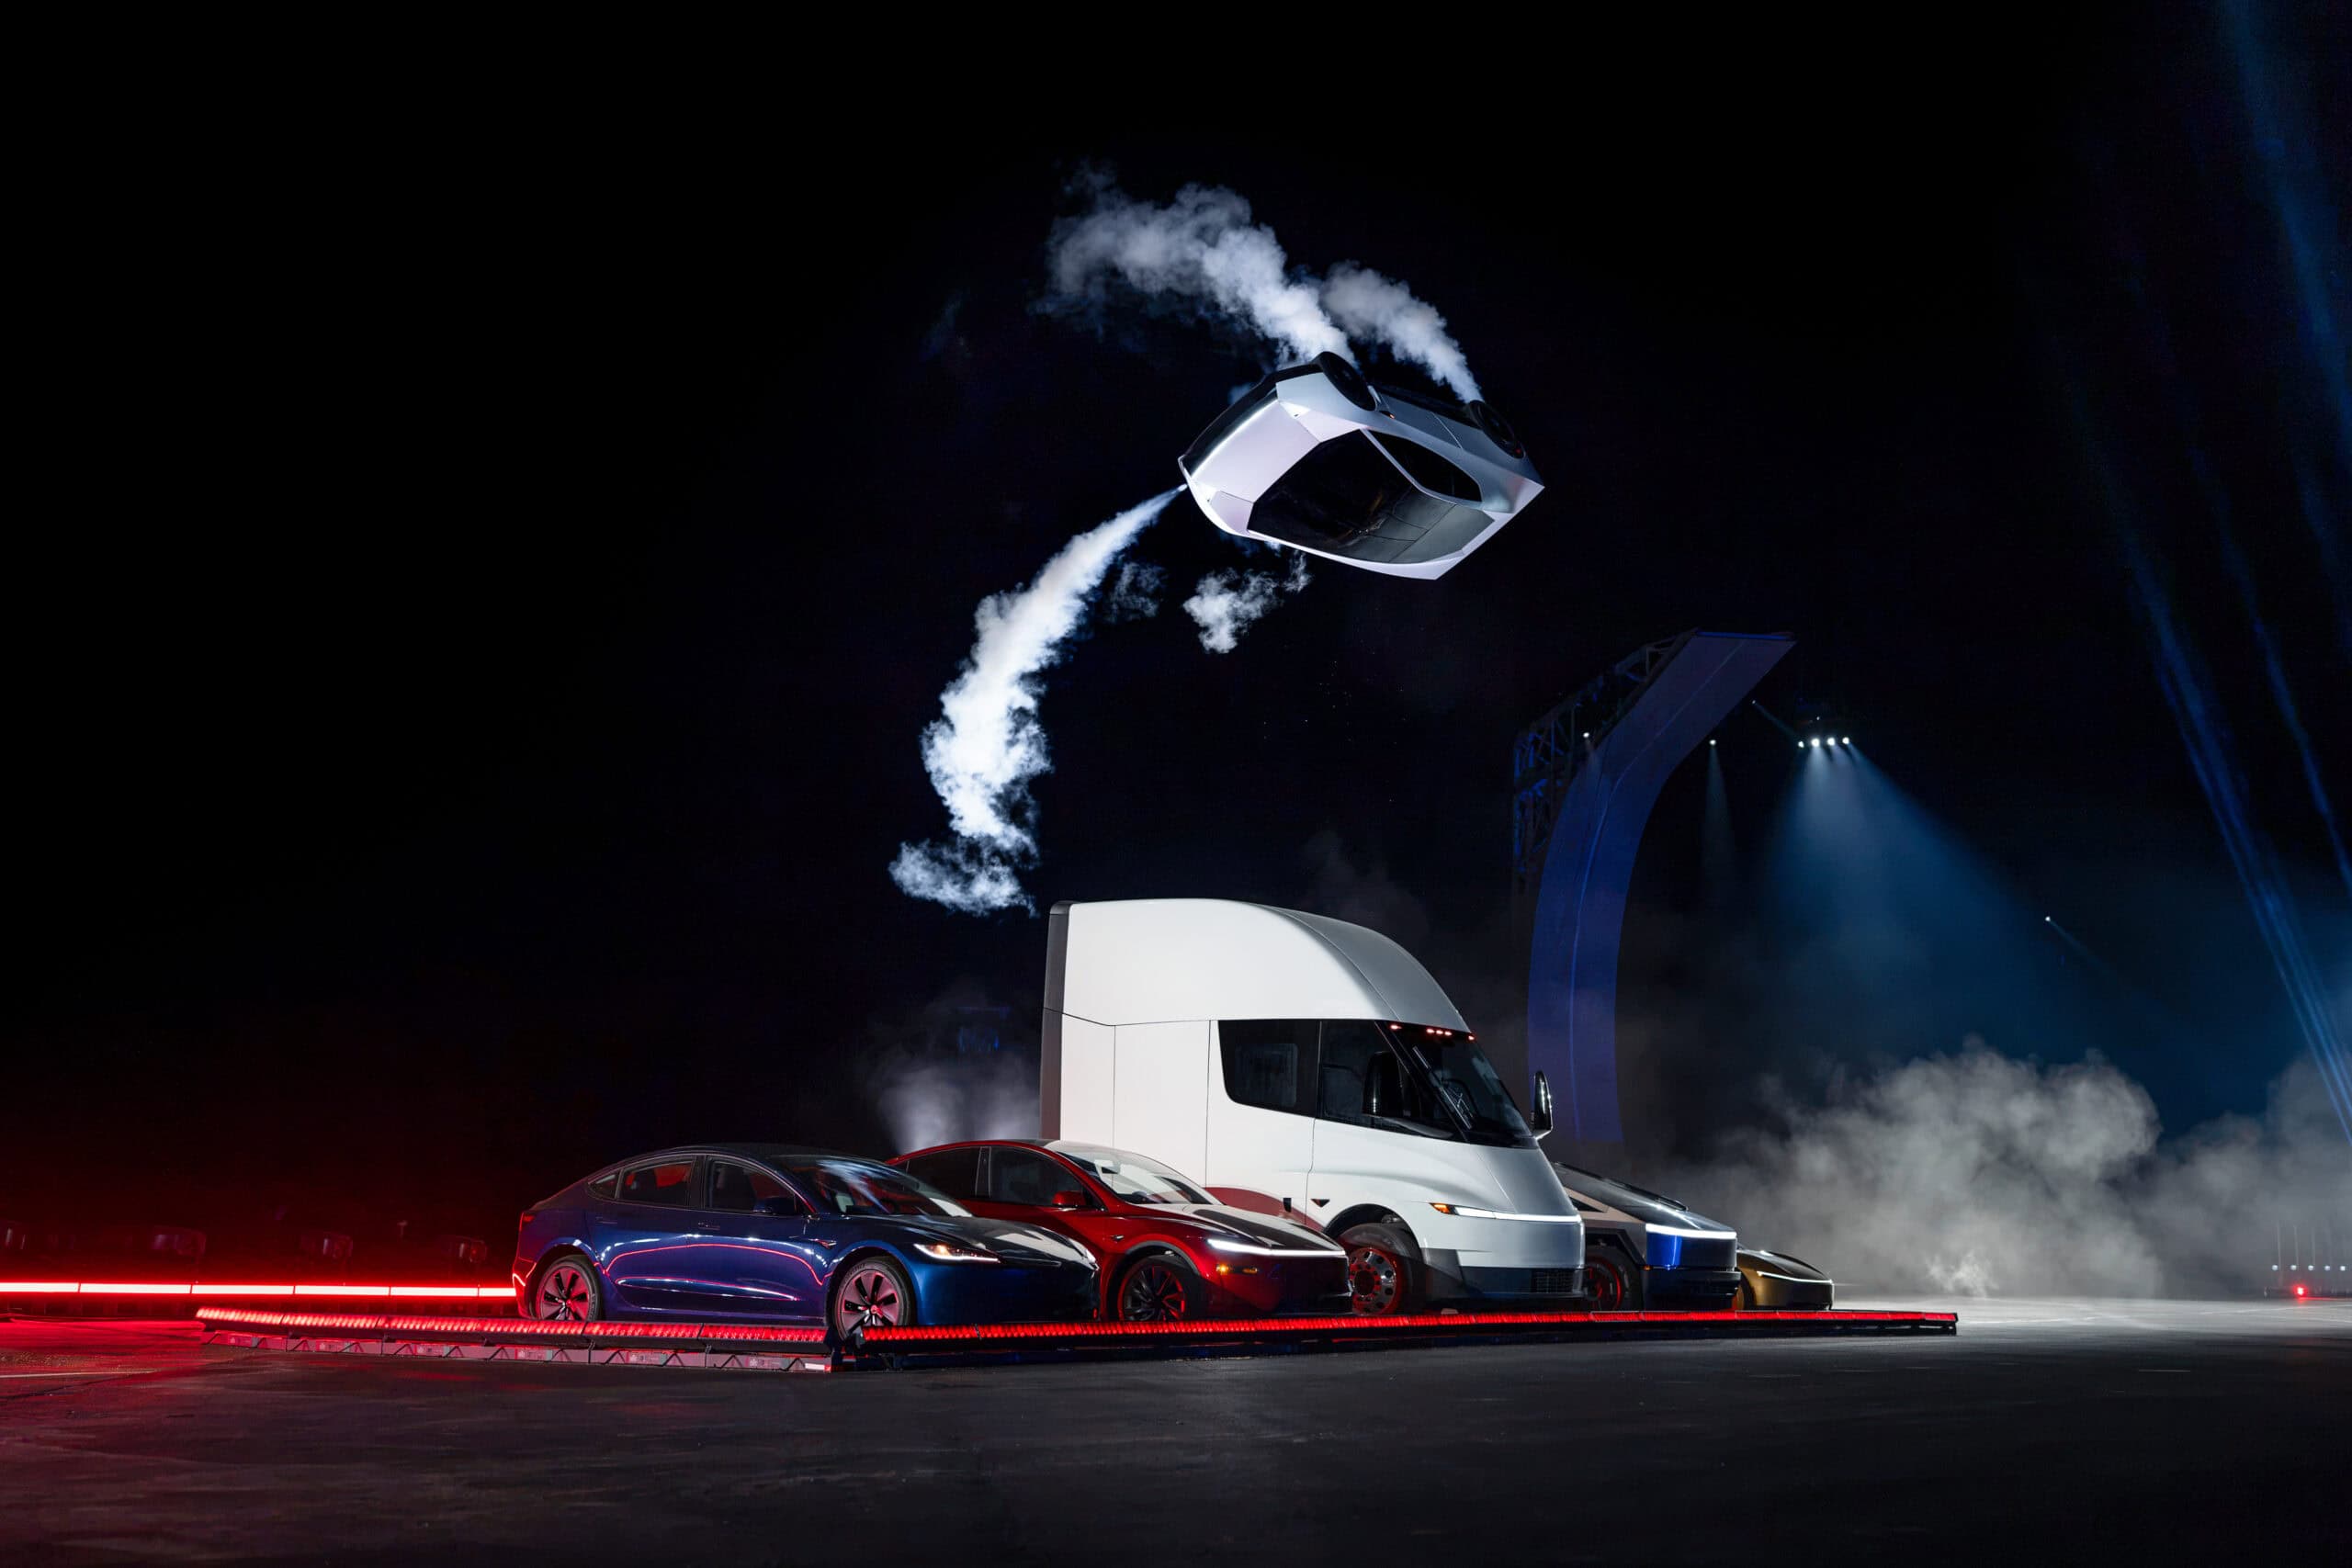
 After Tesla (NASDAQ: TSLA) and Elon Musk presented a next-generation Roadster prototype incorporating SpaceX (NASDAQ: SPCX) derived thruster technology at a demonstration on October 15 at SpaceX’s McGregor, Texas facility, trading activity in instruments tracking Tesla’s share price accelerated sharply on always-open crypto platforms.
The event, which included the vehicle performing aerial maneuvers and flips using cold-gas thrusters and suction systems, occurred after regular US equity markets had closed, with Tesla shares finishing the session at $362.44.
On Hyperliquid, the TSLA perpetual futures contract (listed via Trade.xyz) rose roughly 4.9 percent to around $378 in the hours after the reveal.
Hourly trading volume on the contract increased approximately 1,580 percent, climbing from $2.8 million to $47 million within a single hour.
With the daily candle only about nine hours old at the time of the peak activity, the session ranked as the product’s second-busiest day since listing roughly a year earlier.
Data aggregated by RootData showed Binance leading overall 24-hour volume in Tesla-related derivatives at approximately $279 million, ahead of Hyperliquid’s roughly $159 million.
Hyperliquid nonetheless held the largest open interest, near $99 million.
Tesla’s actual shares indicated roughly 4.5 percent higher in premarket trading the following morning.
SpaceX has used thrusters to position spacecraft for decades.
Making them work in a vehicle instead of a vacuum took all-new hardware & controls.
Every usable void in the car is packed with Carbon Fiber Overwrapped Pressure Vessels (COPVs)
More compressed gas on board = more… pic.twitter.com/IyFDx26yEf
— Tesla (@Tesla) October 16, 2026
The Hyperliquid instrument is a perpetual futures contract that tracks the price of Tesla stock.
It settles in USDC, permits leverage of up to 20 times, and operates continuously without a traditional brokerage account.
This structure allowed market participants to take positions on Tesla’s valuation immediately after the prototype demonstration while the Nasdaq remained closed.
Tesla is scheduled to report third-quarter earnings on October 21.
The episode highlights how round-the-clock crypto derivatives platforms can serve as an initial reaction venue for corporate news that emerges outside conventional equity market hours.
It is important to note that products of this type are frequently mislabeled in headlines and commentary as “tokenized stocks.”
In reality, not all instruments described as tokenized stocks constitute digital securities.
Conflating the two categories reflects a basic lack of understanding of how these financial instruments function.
A genuine digital security representing equity would ordinarily carry ownership rights, potential dividend claims, and the regulatory framework applicable to securities.
Many products marketed as tokenized stocks in crypto markets, including the Hyperliquid TSLA contract, are instead synthetic derivatives or price-tracking perpetuals.
They deliver economic exposure to price moves without conveying ownership in the underlying company, without voting rights, and without the legal character of a security in most jurisdictions.
Treating them interchangeably overlooks material distinctions in counterparty risk, settlement, regulatory status, and holder rights.
These are price-tracking derivatives, not tokenized equity securities.
Many industry professionals and commentators continue to treat every blockchain-based product that references a stock ticker as a form of tokenized equity, often without examining the actual contractual terms, settlement mechanics, or regulatory status.
This habit stems in large part from a failure to read the fine print that defines the instrument.
In the case of the Hyperliquid TSLA contract and similar products listed through platforms such as Trade.xyz, the documentation and market specifications make clear that the offering is a cash-settled perpetual futures contract whose value is derived from an external price feed.
It does not represent a claim on Tesla shares, does not confer shareholder rights, and does not involve the transfer or custody of any underlying securities.
Professionals who overlook these distinctions frequently default to the language of “tokenized stocks” because it is familiar and marketable, even when the product’s structure is that of a leveraged synthetic derivative.
The result is a persistent category error in which price-tracking contracts are discussed as if they were digital representations of equity ownership.
This confusion also reflects a broader shortfall in basic financial literacy among some participants in crypto markets.
Traditional equity ownership, whether in certificated or digital form, is defined by legal rights—including residual claims on assets, potential dividends, voting power, and protections under securities law—rather than by the mere ability to bet on a price.
Perpetual futures and other synthetic instruments, by contrast, are contractual agreements between counterparties (or against a protocol’s risk engine) that expire only when closed, settle in a stablecoin such as USDC, and carry funding rates, liquidation risk, and no ownership interest.
When industry voices blur these categories, they obscure material differences in counterparty exposure, regulatory treatment, and the nature of the claim being traded.
Accurate differentiation requires only the willingness to consult the product specifications and to apply elementary distinctions between ownership of a security and a derivative that tracks its price—distinctions that have long been standard in conventional finance.
Have a crowdfunding offering you'd like to share? Submit an offering for consideration using our Submit a Tip form and we may share it on our site!

