

Why exchanges must let professional capital choose how it is held, not just what it can trade
For most of crypto’s history, institutional adoption was framed as a question of access. Could a fund get exposure at all? That question is largely answered. According to the AIMA and PwC Global Crypto Hedge Fund Report, 55% of traditional hedge funds now have some exposure to digital assets, up from 47% a year earlier. The harder question has arrived: how should that exposure be structured?
The answer the industry is converging on looks a lot like traditional finance. In mature markets, the venue where an investor trades and the institution that holds their assets are rarely the same entity. Crypto grew up the other way, with exchanges acting as broker, venue, and custodian at once. That model helped simplify access during the industry’s early growth, but it does not necessarily meet the governance, operational, and risk requirements of every institutional participant today.
Off-exchange settlement is one way exchanges are separating trading access from asset custody. It lets an institution trade on a venue while eligible assets stay with a third-party custodian, so the exchange provides market access, liquidity, and execution without needing to hold all of the client’s capital. For many firms, that changes how they think about counterparty exposure. However, separating custody from execution does not eliminate risk; settlement obligations, liquidation mechanisms and dependencies on custodians and other service providers remain important considerations.
The benefits are real but specific. Keeping assets with an independent custodian can reduce how much capital is exposed to an exchange and, depending on the structure, allow institutions to support trading across multiple venues without separately pre-funding each one. It also gives auditors and investors a cleaner record of where assets are held. The limitations are just as specific. Exposure may accumulate between settlement cycles, collateral requirements can change during periods of volatility, and each additional service provider introduces operational and legal dependencies. Not every asset or product is eligible, meaning institutions may still need a combination of f on-exchange and off-exchange balances. Off-exchange settlement is a better way to manage exposure, not a way to opt out of it.
The larger issue is that institutional clients are not a single category and exchanges should stop designing their infrastructure as though they are. Asset managers and regulated funds often operate under fiduciary, governance and segregation requirements. For some, independent custody is more than an operational preference. It can determine whether a venue is usable at all. Market makers, high-frequency traders and quantitative firms work differently. They trade across several venues at once, and what matters most is liquidity, fast settlement, and moving trading capacity efficiently between markets. A custody setup built for a pension-backed fund can be a drag on a market maker, and the reverse is just as true.
The differences become clear during due diligence. An asset manager wants to know where assets are held, who can move them, and what happens if the trading venue fails. A market maker is more concerned with how quickly collateral can be redeployed, how often positions are settled, and how much capital sits idle between trades. Both are managing risk, but they measure operational efficiency differently. Exchanges that impose a single custody structure risk making their platforms less attractive to one or both groups.
Today the industry has settled on a handful of models, each suited to a different kind of firm. In one, a custodian holds the assets and mirrors a trading balance onto one or more exchanges, settling profits and losses between them on a regular cycle. That suits multi-venue trading firms, which can deploy the same collateral across several markets without moving it. In another, collateral sits with a regulated bank in a segregated account, and the exchange extends trading capacity against it. That is more conservative, but it maps closely to how a regulated fund already thinks about safekeeping. A third uses technology-enabled custody arrangements, including client-controlled wallets and predefined permissions that govern how assets can be used for trading and settlement. One of these is the right answer for everyone. Each strikes a different balance between speed, capital efficiency, and how far the client’s assets sit from the venue.
The principle is simple. Different types of professional capital should be able to reach the same markets without being forced to manage their assets in the same way. Keeping existing custody arrangements in place also cuts out asset transfers and operational steps that add cost and friction without adding value.
This matters more as exchanges change what they offer. Trading venues are widening beyond crypto, adding tokenized stocks, gold, and other traditional assets alongside digital ones. Widening the range of markets is only half the job. Institutions also need clarity on custody, collateral eligibility, settlement, and how different assets can be managed within existing governance frameworks. Flexibility has to extend to how capital is held and connected, not just to what can be traded.
For exchanges, supporting that choice is harder than it sounds. Each custody model needs its distinct technical integrations, reconciliation process, collateral controls, and its own rules for what happens when a settlement fails or during sudden market volatility. Risk systems have to treat collateral held elsewhere with the same rigour as collateral on the platform. Responsibility must also be clearly defined between the exchange, custodian and client, particularly when assets need to be accessed, positions liquidated or settlement obligations enforced. These arrangements are ultimately tested when liquidity tightens, and operational decisions must be made quickly.
In practice, that means building across several layers at once: third-party custody, settlement connectivity, trading and liquidity, alongside the risk controls and operational transparency institutions expect from established financial infrastructure. None of these is glamorous. All of them decide whether institutional money can participate in a market at scale.
Institutional crypto is becoming an infrastructure story. Professional investors now look past the number of assets on an exchange and ask harder questions about regulation, custody, counterparty exposure, liquidity, and operational structure. The exchanges that answer those questions well will stop looking like retail trading apps and start looking like market infrastructure. That shift is already under way. The venues that build the infrastructure that allows different types of institutions to participate on terms that meet their own requirements are positioned to do better than the others.
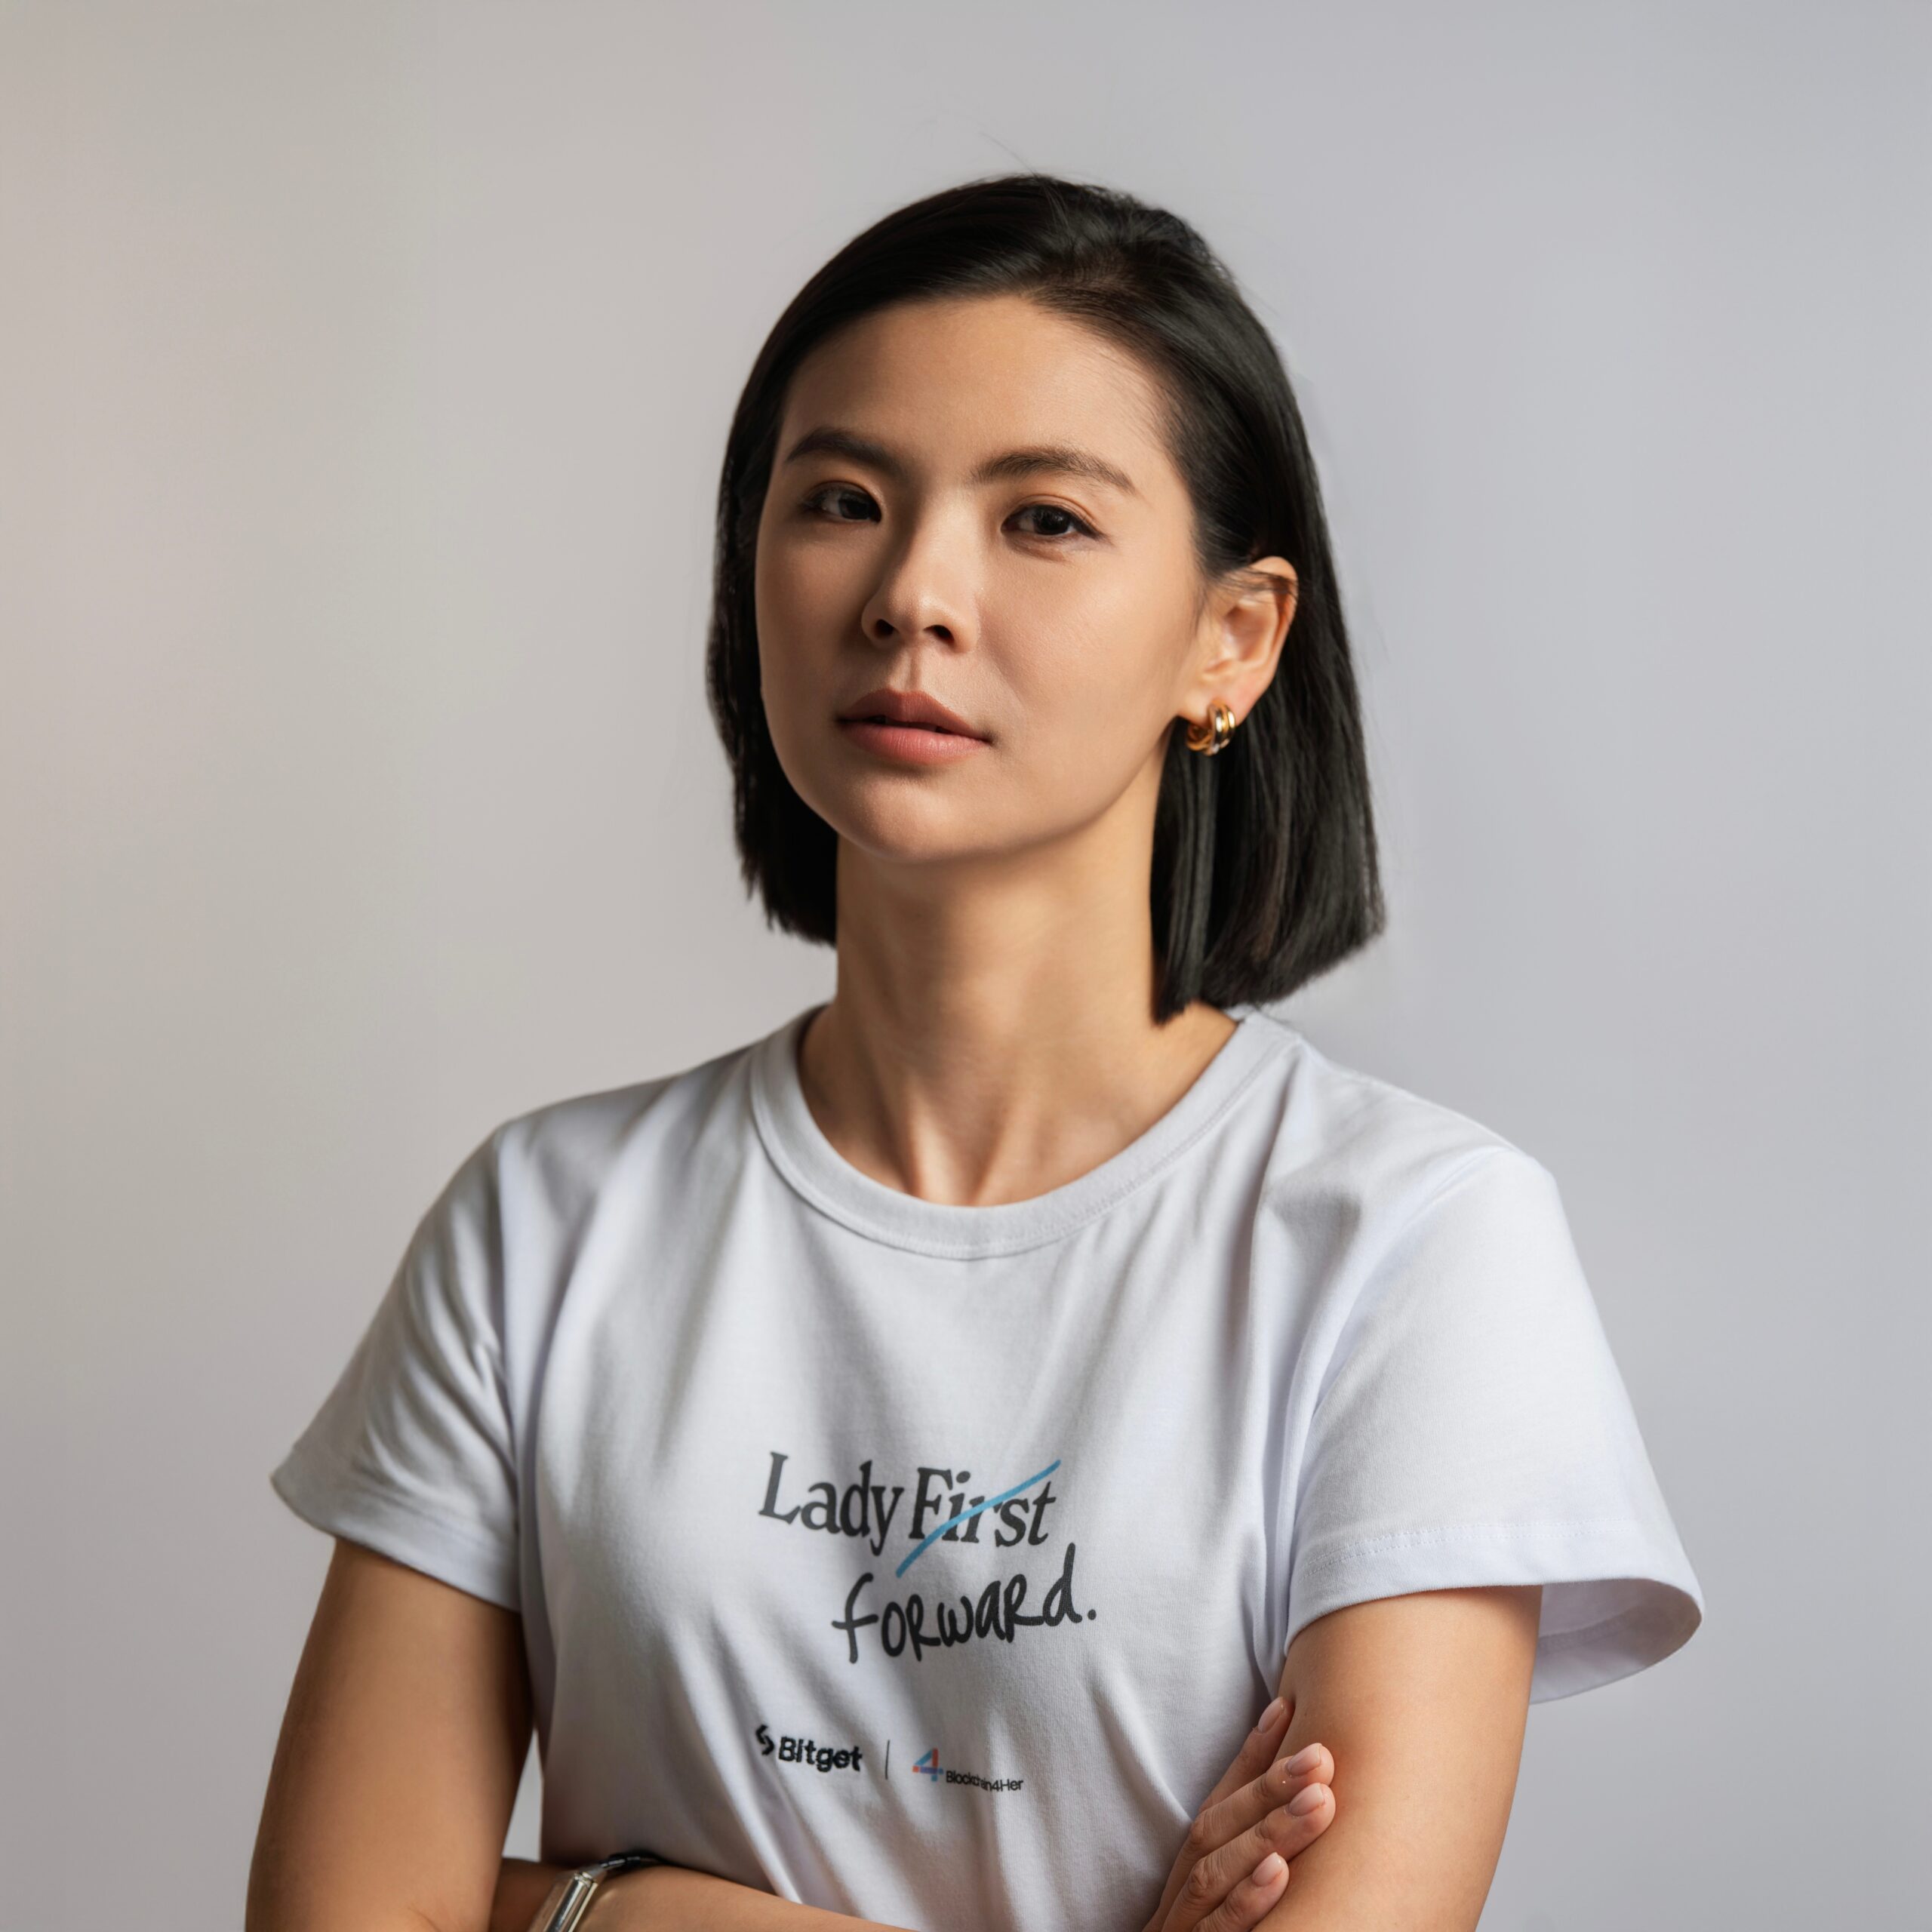 Gracy Chen is the CEO of the cryptocurrency exchange Bitget and the first female CEO among the top ten crypto exchanges globally. Bitget is a Web3 company serving over 125 million users worldwide. She was appointed CEO in May 2024 after serving as Managing Director. She has led Bitget’s expansion into Latin America, Europe, the Middle East, and now the United States. Chen holds a Bachelor’s degree from the National University of Singapore and a Master’s degree from the Massachusetts Institute of Technology (MIT).

