If you are a criminal that steals from others, accepts bribes, or generates income from other malfeasant activities (like dealing drugs), you put yourself at risk of state/local and federal law enforcement authorities. But if you don’t get caught you are still on the hook with the Internal Revenue Service (IRS) to pay taxes on your nefarious activities. Really, it’s true.
In a year of crazy, COVID-induced psychosis, it does not seem that strange that the IRS expects the bad guys to report income from their chosen profession of breaking the law. More specifically, the following activities are taxable just like any other pursuit. To quote the IRS website:
Stolen property. If you steal property, you must report its fair market value in your income in the year you steal it unless you return it to its rightful owner in the same year.
Bribes. If you receive a bribe, include it in your income.
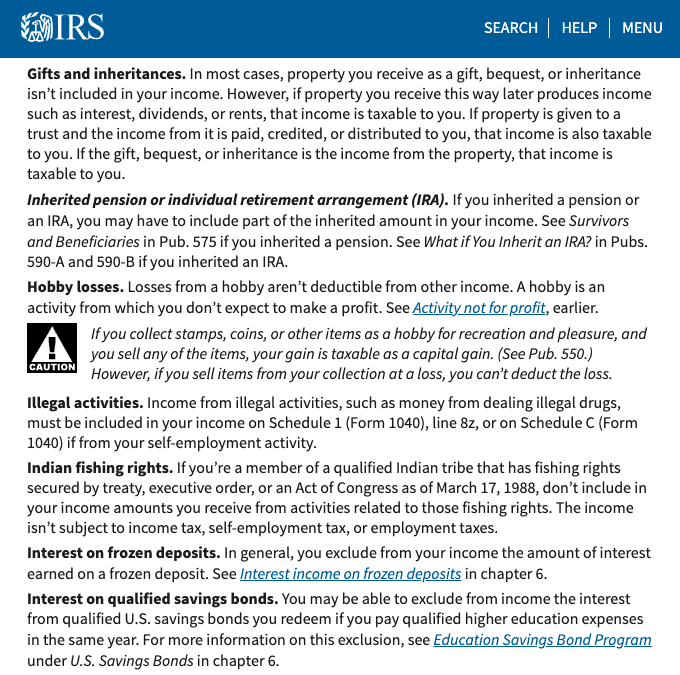
Illegal activities. Income from illegal activities, such as money from dealing illegal drugs, must be included in your income on Schedule 1 (Form 1040), line 8z, or on Schedule C (Form 1040) if from your self-employment activity.
So alongside Jury Duty payments, Rent, and Royalties – not to mention crypto- the above are considered taxable events. Perhaps even if you get caught, except maybe for the stolen property if you decide to return the items within one year of the theft (albeit slightly used).