

“Should the Commission consider doing away with the notion of a so-called “accredited investor” altogether?”
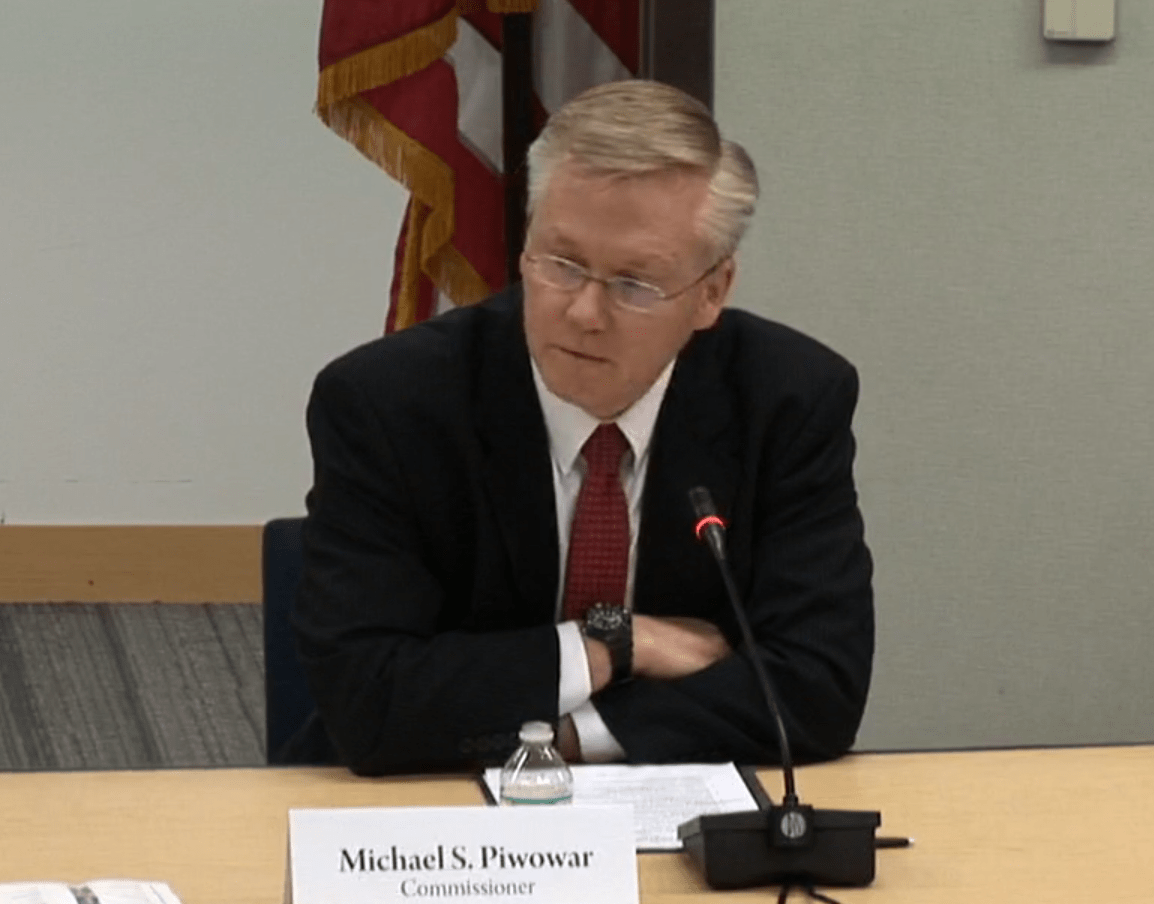
The above question is posed not by this digital publication but by a sitting SEC Commissioner, Michael S. Piwowar.
The Commissioner was speaking at the recent gathering of the Advisory Committee of Small and Emerging Companies (ACSEC) which convened largely to discuss the current definition of an accredited investor.
As it stands today, being accredited means an individual is able to review and decide whether or not they want to invest in certain private placement offers. Companies that are not yet listed on a public market mostly raise capital under Regulation D but only the accredited may join in. The definition was created to save people from themselves and block individuals that earn less than $200,000 a year or have a net worth of one million dollars (minus a primary residence) from making bad (risky) investments. No acknowledgment of experience or sophistication required. Yet in some other countries, such hard line barriers do not exist.
As required by the Dodd-Frank Act, the SEC must review the current definition periodically. The SEC is fulfilling this mandate and, at least on the surface, appear poised to rectify a longstanding act of disenfranchisement of much of the population.
Piwowar, for his part, took a very logical approach. Noting that prohibiting non-accredited investors from investing in high-risk securities is the same thing as prohibiting them from investing in high-return securities, the government is, in effect, becoming an investment advisor.
The Commissioner points to the fact the government has created a “privileged class”. This misappropriation of power means “the government may actually exacerbate wealth inequality and hinder job creation and economic growth.”
Piwowar is correct in asking the Committee, and Commission, to look further as the current policy may be harming “the very investors the policy is intended to protect.”
The remarks are republished in their entirety below.
Commissioner Michael S. Piwowar Remarks at ACSEC Meeting May 18, 2016
Thank you, Sara [Hanks] and Stephen [Graham]. First, I want to welcome everyone — our new committee members, as well as our returning members. I was unable to attend your first meeting in February, but you have hit the ground running. Today’s agenda is quite ambitious and I look forward to hearing the discussions and seeing any resulting recommendations. The committee will be discussing, among things, the accredited investor definition and Regulation D. In fact, the Commission adopted the notion of a so-called “accredited investor” in 1982 when it adopted Regulation D.
In a few minutes, staff in our Division of Corporation Finance will make a presentation of their December 2015 report on the review of the accredited investor definition. Section 413 of Dodd-Frank directs the Commission to review the definition of accredited investor as it applies to natural persons to determine whether it should be adjusted or modified. The staff report fulfills the statutory mandate by providing valuable information on the history of the accredited investor definition and important insights on alternative regulatory approaches. After the staff presentation, the Committee will discuss the accredited investor definition. I am sure that there will be a lively discussion about alternative accredited investor definitions.
But I want to ask the Committee to consider going beyond that discussion after today’s meeting before making any recommendations. Take a step back and ask the question: should the Commission consider doing away with the notion of a so-called “accredited investor” altogether? As I have said before, it essentially divided the world of private offering investors into two arbitrary categories of individuals — those persons who were accorded the privileged status of being an “accredited investor” and those who were not. In short, if you made $200,000 or more in annual income or had $1 million or more in net worth, then you were in the privileged class and could choose to invest in the full panoply of investments, whether public or private. If not, the government decided that, for your own protection, you were restricted access to these private investments.
The Committee has the opportunity to move beyond the artificial distinction between so-called “accredited” and “non-accredited” investors and challenge the notion that non-accredited investors are in fact “being protected” when the government prohibits them from investing in high-risk securities. For example, the Committee could do as I do and appeal to two well-known concepts from the field of financial economics. The first is the risk-return tradeoff. Because most investors are risk averse, riskier securities must offer investors higher returns. This means that prohibiting non-accredited investors from investing in high-risk securities is the same thing as prohibiting them from investing in high-return securities.
The second economic concept is modern portfolio theory. By holding a diversified portfolio of assets, investors reap the benefits of diversification; that is, the risk of the portfolio as a whole is lower than the risk of any individual asset. I do not have the time today to give a full lecture on the mathematics and statistics of portfolio diversification, so I will just assure you the correlation of returns is key. When adding higher-risk, higher-return securities to an existing portfolio, as long as the returns from the new securities are not perfectly positively correlated with (move in exactly the same direction as) the existing portfolio, investors can reap higher portfolio returns with little or no change in overall portfolio risk. In fact, if the correlations are low enough, the overall portfolio risk could actually decrease.
These two concepts show how even a well-intentioned investor protection policy can ultimately harm the very investors the policy is intended to protect. Moreover, restricting the number of accredited investors in the “privileged class” can have additional (or what economists call “second-order”) effects. The accredited investors may enjoy even higher returns because the non-accredited investors are prohibited from buying and bidding up the price of, high-risk, high-return securities. As a result, small businesses face higher costs of capital. Remarkably, if you think about it, by allowing only high-income and high-net-worth individuals to reap the risk and return benefits from investing in certain securities, the government may actually exacerbate wealth inequality and hinder job creation and economic growth. This is just one suggestion for the Committee to consider after today’s meeting. In any event, I look forward to an informative discussion.
Thank you.

