

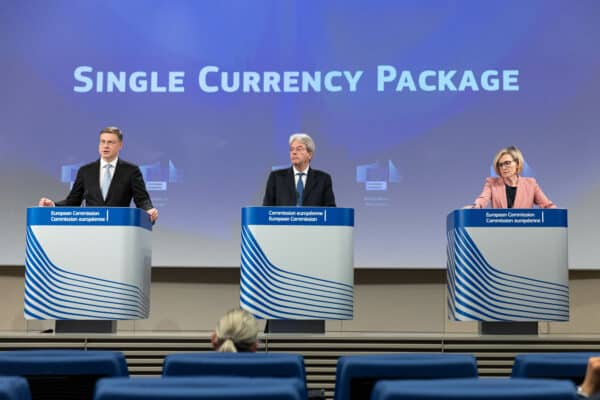
Like many other jurisdictions, the European Union has been reviewing the potential to launch a digital Euro, and today, the EU took another step in that direction.
As expected, the EU issued a proposal to create a digital Euro which seeks to satisfy the needs of diverse constituencies, including a desire for heightened privacy.
EU Executive Vice-President Valdis Dombrovskis said the Euro is a European success story that symbolizes strange and unity but as more people choose to pay digitally, the Euro should adapt to the digital age.
“A digital Euro would complement cash but not replace it,” said Dombrovskis. “Today’s proposals will also make sure that cash will continue to be fully available while allowing the European Central Bank to develop, over time, the practical aspects of the digital Euro. It would be safe and secure, instant and convenient – online and offline – offering more consumer choice alongside with private digital payment options such as cards and apps. And it would be available for everyone to use, free of charge and with strict data privacy.”
The European Commission has proposed two sets of measures that aim to ensure that both digital and physical payment options remain.
The legislative proposal would safeguard cash while creating a framework for a CBDC or central bank digital currency. This would be in addition to private options.
The final decision as to whether or not to issue a digital Euro will be for the ECB to decide.
As part of the proposal, it is expected that a digital currency would be able to exist alongside cards or “applications.” It would work in a digital wallet with individuals able to pay anytime anywhere, online and offline.
Online transactions are expected to provide the same level of data privacy as existing digital means of payments, addressing a nagging concern about the potential for government abuse of personal privacy.
Merchants would be required to accept the digital Euro, with the exception of very small businesses.
There is an expectation that a digital Euro would be a “solid basis for further innovation” without examples being provided.
In a speech, EU Commissioner Mairead McGuinness said they are also strengthening against payment fraud by introducing a new right to a refund to consumers who are victims of certain types of fraud like spoofing when consumers get tricked into transferring money to them.
Open banking is part of the equation as well, and the proposal is “about putting innovation at the service of consumers.”
Alisa DiCaprio, Chief Economist at R3 – a permission blockchain provider, said the proposal for a European CBDC is acting as a foundation for a future privacy framework.
“Some members of the public may still have lingering concerns around CBDCs linked to privacy, so having the right design framework and technology in place can help address and alleviate these potential barriers to adoption,” sai DiCaprio. “Additionally, the introduction of specific smart and targeted regulation should be embraced to ensure that user data is kept private. Targeted regulation can act as a funnel for innovation, providing trust and transparency by creating clear guidelines on how the technology is applied.”
She added that collaboration between the ECB, tech providers, and regulators will be key to a solid design process.
The investigation phase of the digital euro will conclude in October 2023, with an actual digital currency still several years out if approved.

