

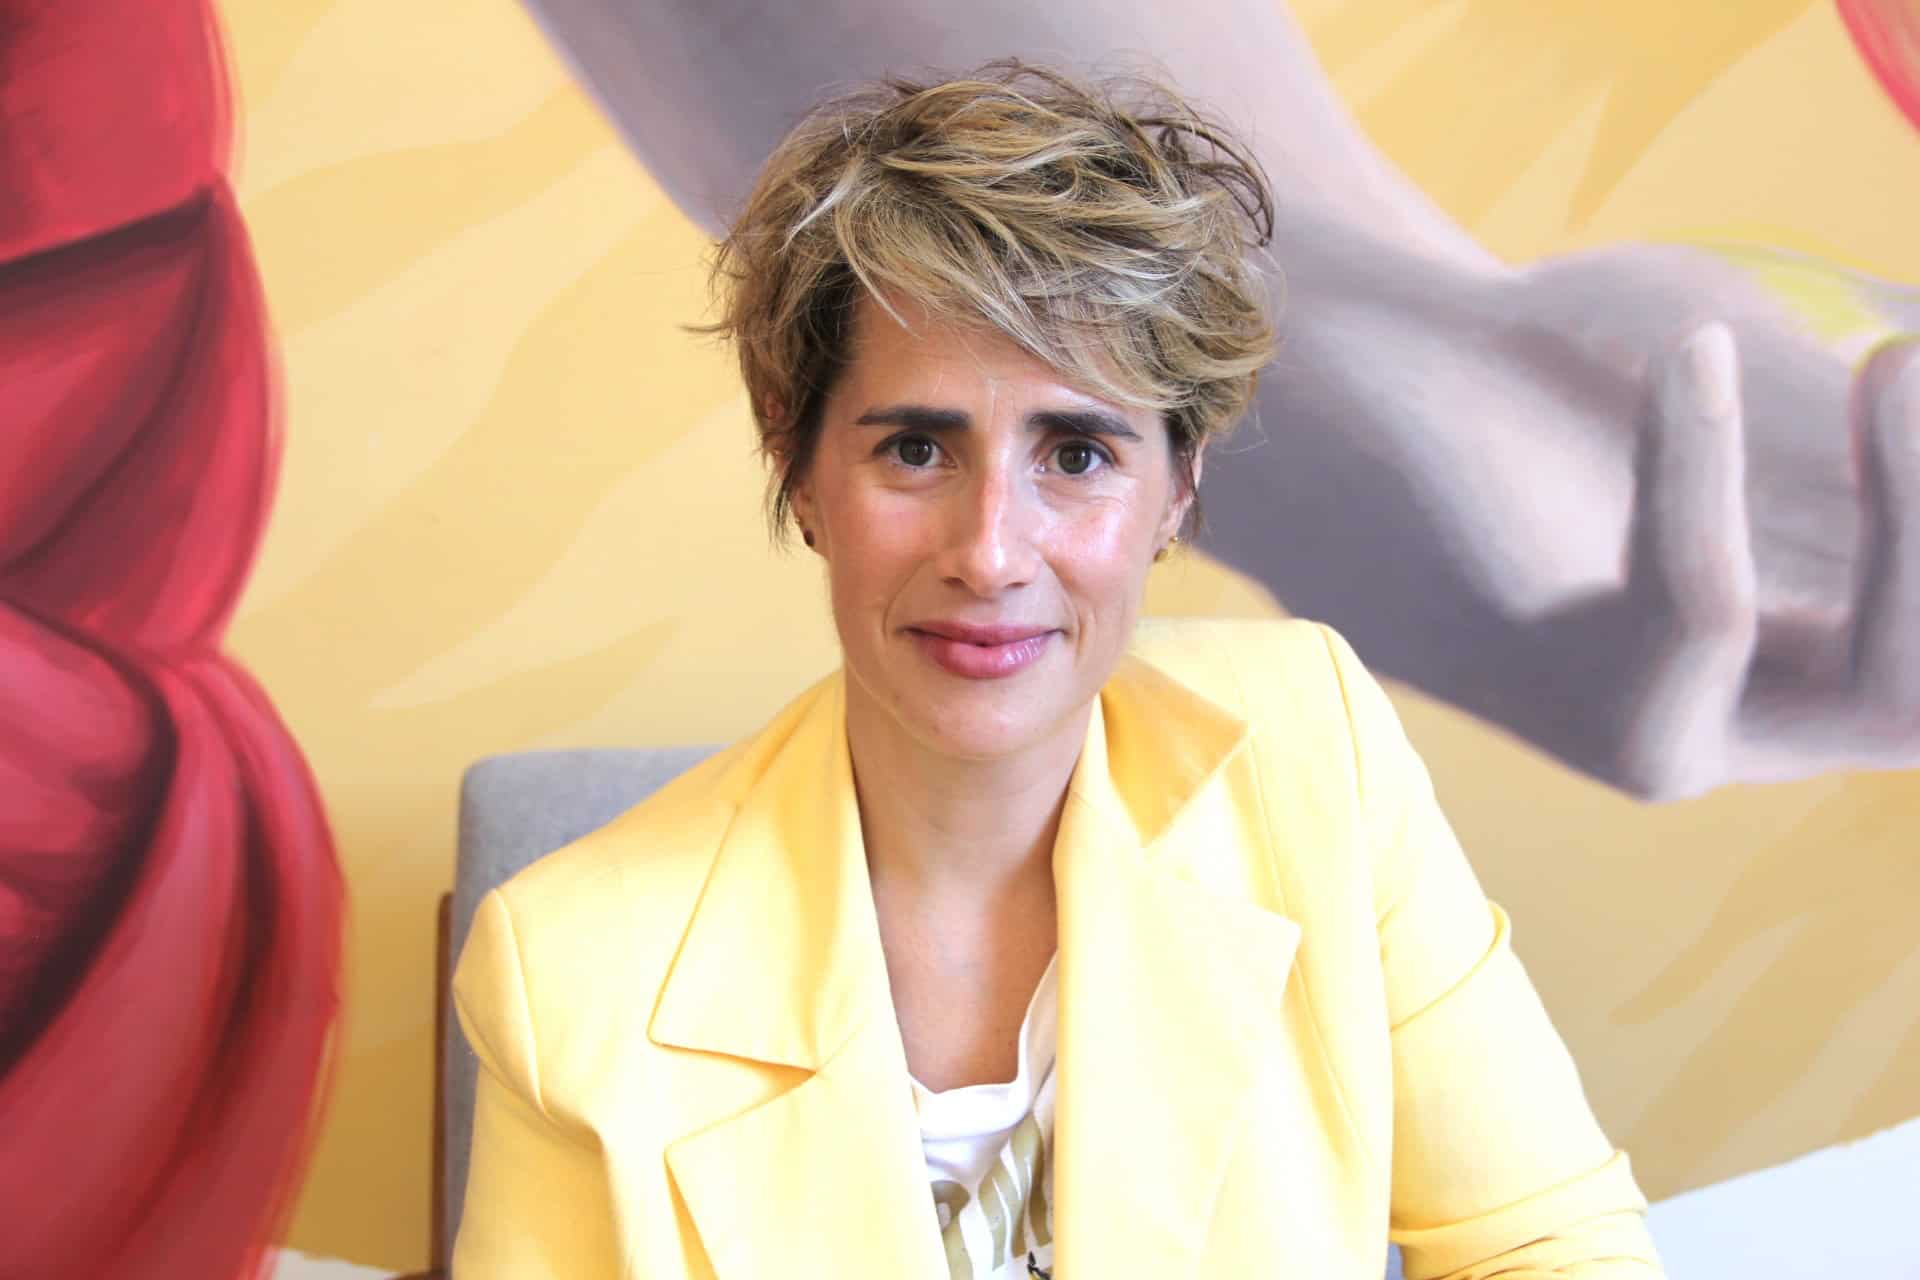
As Open Banking becomes more popular in Latin America, Prometeo is well-positioned to be a major player in the space. Prometeo’s partners, a provider of a single API connecting businesses to every bank in 11 countries, include Santander, Bancolombia, Banco de México, and Chile’s Banco Estado.
Prometeo co-founder and co-CEO Ximena Aleman said Latin America is fertile territory for Fintech innovation. There’s a hunger to disrupt traditional finance, more than exists in Europe and the United States. That’s because when entrepreneurs see an opportunity to improve on what exists, they seize it.
And there is opportunity in Latin America. When she began her Fintech career a decade ago (Aleman previously founded two other companies), “Fintech” wasn’t even a word in Uruguay; Aleman was simply building something useful.
Those experiences taught her that Latin America lacked API infrastructure.
“I understood that was a bottleneck for Fintech disruption,” Aleman said. “It was a bottleneck for my two previous startups. It was a long discovery process of understanding how the financial sector works in Latin America; which are the struggles of large corporations and the struggles of entrepreneurs trying to build new things. The lack of 21st-century infrastructure became obvious to us.”
Solving problems by improving UX
Latin America has a range of concerns, from socioeconomic to a lack of experience. Aleman said entrepreneurs cannot singlehandedly solve issues like poverty and currency devaluation, but they can tackle many others.
In Latin America, she said money is hard to earn, withdraw from an ATM, invest, save, and even deposit in the bank. That poor user experience creates a perception that money is problematic. That’s where the Ximena Alemans come in.
“My generation of entrepreneurs, we’re trying to change that feeling around money, that it can feel different,” she said. “It can be easier, faster, smoother. Hopefully, in the next 20 years, we’ll see that change.”
Prometeo seeks to bridge the infrastructure gap between countries via a single API. That’s crucial in a region where Brazil’s infrastructure differs widely from Uruguay’s or Colombia’s. Through that single integration, Prometeo connects to more than 1,000 financial institutions in 11 countries. It simplifies account consolidation, balance management, and cross-border visibility.
“It’s something that we’ve built since 2021, and is one of those things that, once you have it, you don’t understand why for so many years, you didn’t,” Aleman said.
Prometeo seeks to bridge the infrastructure gap between countries via a single API
How Prometeo works with regulators
Aleman is also an educator. She works with regulators about Open Banking. Five years ago, it was a challenge to convince them it was coming. Over the past two years, they described best practices from different countries and shared their experiences with them. Regulators make suggestions, and entrepreneurs adapt.
That maturation is welcome; Aleman said it’s what she hoped for five years ago. It’s finally happening in Latin America. She understands the trepidation. Regulators usually address what already exists, not what could come next.
If you think that hurdle is hard in the United States or European Union, where there is one regulator, try Latin America, where there could be 20 approaches. Still, Aleman said innovators feel they have a place at the table and regulators are listening. In such a climate, things can happen.
They’re happening in Brazil, which Aleman said has set an impressive precedent for what Open Banking and payment innovation can do for a country, Chile has a straightforward regulatory approach that brings certainty. Still, there are many different approaches, which are both a challenge and an opportunity.
“That helps Prometeo create value because we are unifying these different open value schemes,” Aleman said.
Progress with stablecoins and new payment rails
While stablecoins won’t see wide adoption in 2025, Aleman expects its use, especially USDC, to surge by 2027. It has utility for both direct-to-consumer and corporate use. Many large financial institutions are adopting USDC for cross-border payments and remittances.
“The cross-border space is ripe for disruption, definitely,” Aleman said. “That’s the huge trend that we will see in the upcoming years. I think that USDC is a part of that.”
Progress continues with replacing the old payment rails. More players are assuming the challenge of how to make money flow through those pipes. Aleman said to expect more interoperability in the next few years.
Improvement begins with B2C, but Aleman said the true opportunity lies in the larger cash flows of B2B. Part of the solution is to recognize that the process isn’t just a money flow, it’s also a data exchange.
“Something that Prometeo’s tried to push in our offering is not only the cross-border payment flow but also the cross-border data flow that enables, reconciles and conciliates the payment flow,” Aleman said. “That’s where open banking becomes relevant. Once you understand that you have to move the money, you also have to make sure someone understands that the money has been moved, and you need to reconcile the payment. You need small pieces of data in real-time, in an automated manner.”
“An API that can provide context and visibility on the cross-border payment and cross-border data flow, is also very relevant.”

