

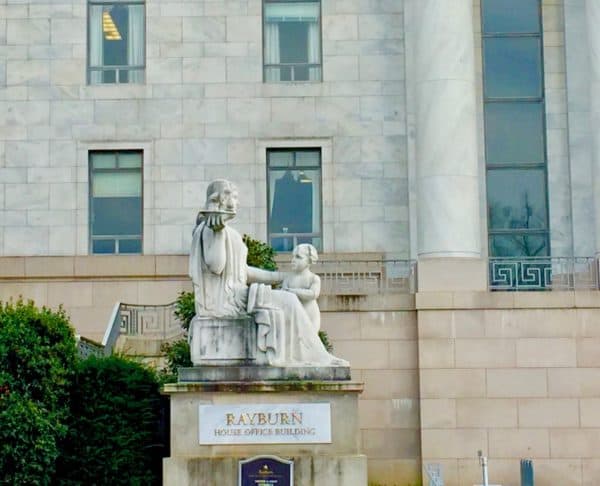
The Congressional subcommittee on Capital Markets, Securities, and Investment Enterprises, has scheduled a hearing on the topic of US equity markets. Entitled,“U.S. Equity Market Structure Part I: A Review of the Evolution of Today’s Equity Market Structure and How We Got Here,” is scheduled to take place on Capitol Hill on June 27 beginning at 10AM. The hearing are typically live streamed on the Financial Services Committee website.
This is a two—panel hearing with the following witnesses:
Panel I
- Matt Lyons, SVP and Global Trading Manager, The Capital Group
- Joseph Saluzzi, Partner, Themis Trading LLC
- Ari Rubenstein, CEO, Global Trading Systems (GTS)
- Jeff Brown, SVP, Legislative & Regulatory Affairs, Charles Schwab
Panel II
- Thomas Farley, President, New York Stock Exchange
- Brad Katsuyama, CEO, The Investors Exchange (IEX)
- Chris Concannon, President and COO, Chicago Board of Options Exchange
- John Comerford, Head of Global Trading Research, Instinet
- Tom Wittman, EVP and Global Head of Equities, NASDAQ
The hearing will review the current state of the US equity markets and how the current structure has evolved since the enactment of the Securities Acts Amendments of 1975 (Pub. L. 94-29), which established a new national market system for securities.
The hearing memo states that despite significant technological advancements and constantly evolving industry practices in today’s
market, the statutory framework that governs equity market structure remains largely unchanged.
The Securities and Exchange Commission governs equity market structures, including Regulation National Market System (NMS). The Subcommittee intends to analyze what is working well in today’s equity markets, what needs improvement, and any impediments to the optimal functioning of the equity markets. There has been a lot of recent discourse on the efficacy of public markets and the rising importance of private markets. More and more companies are staying private longer to avoid going public. The reasons behind the fact companies try and avoid trading on a public exchange typically focus on cost, regulatory burden and simply due to the fact there is plenty of private capital available without going public. In fact today, going public is more of an exit than an entry as it allows early shareholders an ability to cash out.

